Documentation, not adjusting
Roof Insurance Claims in Rosharon, TX
Three provisions decide what your Texas roof claim pays, and they stack: the percentage deductible, whether the roof settles at actual cash value, and whether a roof payment schedule is attached. Here is all three, in plain English.
Under Texas House Bill 2102, in force since 2019, a roofing contractor who pays, waives, rebates or credits your insurance deductible commits a Class B misdemeanour, punishable by up to $2,000 and up to 180 days in jail. A homeowner who knowingly participates is exposed as well. It reaches absorbing the deductible inside an inflated estimate, cash back, gift cards and "free roof" advertising.
Start there, because it is the fastest way to sort the roofing companies in this county into two piles. What follows is everything else worth knowing before you file.
Your wind and hail deductible is a percentage, not a number
Texas homeowners' policies apply a percentage deductible to wind and hail losses rather than a flat dollar figure, and 2 percent is now the dominant standard with 3 percent spreading in high-frequency areas. Two percent of a $400,000 dwelling limit is $8,000. That is the amount you pay before the carrier contributes anything, and it is calculated on the insured value of the house rather than on the size of the claim.
Read your declarations page and find the actual figure. A surprising number of people discover their deductible for the first time in the week after a hurricane.
Then check how the roof itself is settled
Many Texas policies insure the dwelling at replacement cost while settling the roof at actual cash value, which means depreciation for age is deducted before anything is paid. Others attach a roof payment schedule endorsement, which scales the payout down by roof age on a published table. A fifteen-year-old roof under a roof payment schedule can settle at 30 to 40 percent of replacement cost.
These provisions stack with the deductible, and the order matters. The carrier depreciates first, then subtracts the full percentage deductible from what is left. That arithmetic is how a $22,000 replacement turns into a five-figure gap that nobody warned you about.
| Provision | What it does | Typical effect on a $22,000 roof |
|---|---|---|
| Percentage wind/hail deductible | 2% of dwelling limit, not of the claim | $8,000 on a $400,000 home, before anything else |
| Actual cash value roof settlement | Depreciates the roof for age before paying | A 15-year-old roof pays a fraction of replacement |
| Roof payment schedule endorsement | Scales payout down by roof age on a table | 30–40% of replacement cost at 15 years |
| Replacement cost value, no schedule | Pays depreciation back once work is done | Full cost less the deductible, in two payments |
| TWIA policy, no WPI-8 on file | 1988–2009 builds insurable with a surcharge | 15% surcharge on the premium, ongoing |
| TWIA building code credit | Credit for certified code-compliant construction | 19% to 33% off the wind premium |
Deductible and settlement structures from 2026 Texas homeowners' policy analysis; TWIA surcharge and code credit figures from the Texas Department of Insurance TWIA Overview published 8 June 2026.
What we do, and what we deliberately do not
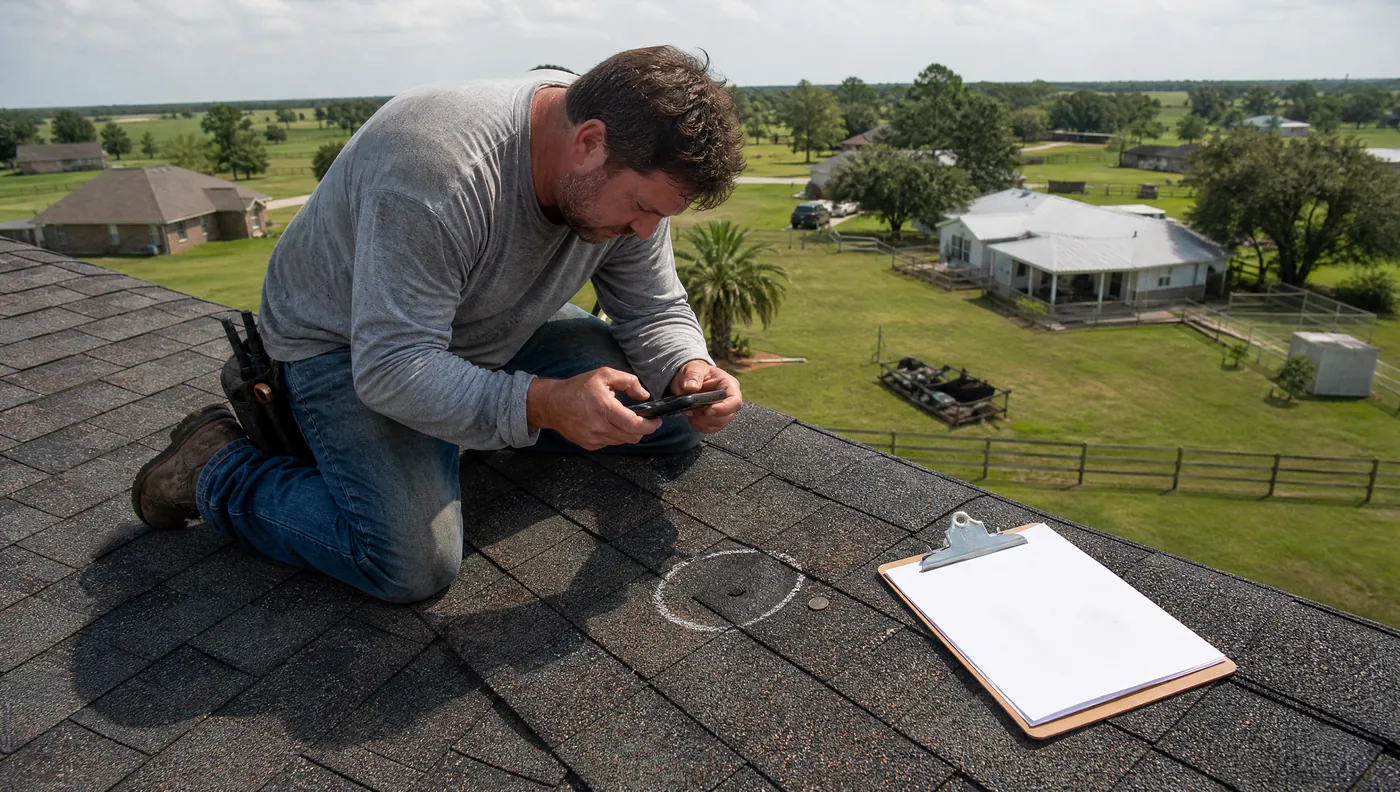
Our job on a claim is documentation and repair. Somebody walks the roof, photographs every point of damage against a scale, notes the date and the storm, measures the roof properly, and produces a written line-item scope of what putting it right actually requires. That is the document that gets attached to a re-inspection request when a carrier's first estimate misses things.
What we do not do is negotiate your claim, interpret your policy for you, or tell you what you are entitled to. In Texas a roofing contractor is not permitted to act as a public insurance adjuster on a job they are contracting for, and the ones who blur that line are usually the same ones offering to handle your deductible. If your claim genuinely needs advocacy, a licensed public adjuster or an attorney is who you want, not your roofer.
The TWIA question, if you are on TWIA
More than half of Brazoria County now buys wind and hail coverage from the Texas Windstorm Insurance Association: 39% of the residential market in 2023, 47% in 2024, 51% in 2025. If that is you, two things follow. Re-roofs must comply with the required windstorm building codes to remain eligible for coverage, and the certificate that proves it earns a building code credit worth 19% to 33% of the wind premium.
The WPI-8 explained, or the full county data if you want the underlying tables.
What order should you do things in?
Photograph the damage, notify your carrier, then get an independent documented inspection. That order matters. Notifying late gives a carrier room to argue the damage came from something else; getting an inspection before you notify sometimes means you file a claim you did not need. Repairs come last, apart from emergency mitigation, which comes first and should itself be photographed.
Should you file at all?
Not always. If the repair costs less than your deductible there is nothing to claim and filing anyway puts a claim on your record for no money. On a $8,000 deductible and a $1,400 repair, the answer is obvious. The awkward cases are in the middle, and the honest way through is to get the repair priced first and then decide with a real number in front of you rather than a guess.
Texas House Bill 2102 penalties per the Texas Insurance Code as summarised by industry counsel; deductible and settlement structures from 2026 Texas policy analysis; TWIA figures from the TDI TWIA Overview. None of this is legal or insurance advice, and we are neither lawyers nor adjusters.
Where we do this work
Claim documentation across the whole service area. The carrier does not care which town you are in, but the permit authority for the repair does.
Insurance Claims in Iowa Colony, Arcola insurance claims, Insurance Claims for Manvel properties, Insurance Claims in Fresno, Sienna insurance claims, Insurance Claims for Brookside Village properties, Insurance Claims in Pearland, Alvin insurance claims, Insurance Claims for Missouri City properties, Insurance Claims in Damon, Angleton insurance claims, Insurance Claims for Danbury properties, Insurance Claims in Liverpool.
Related: Storm & Hail Damage Roof Repair · Windstorm Inspection & WPI-8 Certification · Roof Inspection & Written Estimate · Roof Replacement & Tear-Off
Get your roof damage documented properly, free
Photographed, measured, dated and written up as a line-item scope. Whether you claim or not is your call and we have no stake in it.
Call (281) 845-8668- We document, we do not adjust, and the difference is the law
- No deductible games, ever
- Written scope you can hand to your carrier
Have a doubt
Roof insurance claim questions
Is it illegal for a roofer to cover my deductible in Texas?
Yes. Texas House Bill 2102 makes it a Class B misdemeanour for a contractor to pay, waive, rebate or credit a homeowner's insurance deductible, with penalties up to $2,000 and up to 180 days in jail, and a homeowner who knowingly participates is exposed as well. It covers absorbing the deductible in the estimate, gift cards, cash back and free-roof advertising. Anyone who offers has told you what you need to know about them.
Why is my insurance only paying half the cost of the roof?
Almost certainly because the roof is settled at actual cash value or has a roof payment schedule attached, and then the full percentage deductible comes off what is left. Check your declarations page for the wind and hail deductible percentage and for a roof settlement endorsement. Those two lines explain most of the gap.
Can you help me fight my insurance company?
No, and be wary of any roofer who says yes. In Texas a contractor may not act as a public insurance adjuster on a job they are contracting for. What we can do is document the damage thoroughly and produce a scope that shows what the repair genuinely requires, which is what a re-inspection request is built on. If you need somebody arguing on your behalf, that is a licensed public adjuster or an attorney.
My carrier dropped me after the claim. What now?
TWIA exists for exactly this and it is why its Brazoria County market share went from 39 percent to 51 percent in two years. You will need a declination from at least one licensed insurer writing wind and hail in the first-tier counties, and, if the house was built on or after 1 January 1988, windstorm certification for the construction. Talk to your agent early rather than at renewal, and if the roof is due anyway, do it in the order that gets you certified.
Do I have to use the contractor my insurer suggests?
No. You choose who works on your house. A carrier's preferred-vendor programme is a convenience, not an obligation, and using an independent contractor does not affect what the policy pays. What does affect it is the scope of work being documented properly, whoever writes it.